Most Common Reason Insurance Claims Get Denied (Roofing Guide)
The most common reason roof insurance claims get denied is a lack of proper documentation proving the damage is storm-related and severe enough to warrant a full replacement. In plain English: the adjuster either couldn't see the damage, didn't believe it was caused by hail or wind, or blamed it on age and wear-and-tear instead of the storm. Here at Advantage Roofing Company in Tyler, Texas, we see this all the time — good homeowners with real damage getting a denial letter simply because nobody fought their corner. The good news is that a denial is not the end of the road, and I'm going to walk you through exactly why claims get shot down and what you can do about it.
1. Lack of Documentation Is the #1 Reason Roof Claims Get Denied
Let me be straight with you — most denials come down to paperwork and proof, not the actual condition of your roof. When an adjuster shows up, they're looking for clear, documented evidence that a specific storm caused specific damage on a specific date. If that evidence isn't laid out for them in black and white, they'll take the easy road and deny the claim or lowball the estimate. That's just how the game is played, and after nearly 18 years I've watched it happen over and over.
The insurance company isn't in the business of handing out money. According to the National Association of Insurance Commissioners, homeowners have the right to documentation and a clear explanation for any denial — but most folks don't know to ask, and they don't have anybody in their corner who speaks the adjuster's language.
- Missing "date of loss" tied to a verified storm event
- No photos of hail bruising, granule loss, or wind-lifted shingles
- Damage written off as normal aging or "wear and tear"
- No professional inspection report backing up your claim
Pro Tip: Before you ever file, get a licensed local roofer up on your roof to document everything with photos and a written report. That paper trail is the difference between an approval and a denial.
2. Storm Damage Blamed on Age and Wear-and-Tear
Here's a sneaky one that trips up a lot of homeowners around East Texas. Even when there's real hail or wind damage, adjusters will often chalk it up to "age" or "normal deterioration" — because if it's wear-and-tear, they don't have to pay a dime. Your policy covers sudden storm damage; it does not cover a roof that simply got old. So the whole battle becomes proving your damage came from the sky, not the calendar.
This is exactly where having somebody who knows both sides of the fence matters. Hail leaves a specific signature — round bruises, knocked-off granules, soft spots. Wind leaves creased and lifted shingles. Age looks completely different. If you can't tell the difference, the adjuster's version wins by default.
- Hail damage shows random, circular impact marks with granule loss
- Wind damage shows creased, torn, or missing shingles along edges
- Aging shows uniform granule loss and curling across the whole roof
- Documenting the difference is what gets a "denied" flipped to "approved"
Pro Tip: Don't let an adjuster's first opinion be the final word. A second set of trained eyes often finds storm damage that got missed or mislabeled.
3. Filing Too Late After the Storm
Time is not on your side with insurance claims, and waiting too long is one of the fastest ways to get denied. Most policies have a filing deadline, and the longer you wait, the harder it is to prove that a particular storm — and not the last three years of Texas weather — caused your damage. I've talked to plenty of homeowners who noticed a stain on the ceiling, figured they'd deal with it later, and by the time they filed, the window had closed.
Here in East Texas our storm season really cranks up from February and March on through summer, and hail can do damage you can't even see from the ground. That's why I always tell folks: after any significant storm, get an inspection even if your roof looks fine. Catching it early keeps your claim alive.
- Review your policy for the exact claim filing deadline
- Document the storm date with local weather records
- Get inspected right after a storm, not months later
- Report new leaks or interior damage immediately
Pro Tip: Keep a simple note on your phone every time a big storm rolls through Tyler — date and what you saw. That timeline becomes gold if you ever need to file.
4. Not Meeting Your Policy Requirements or Deductible
Another common denial reason has nothing to do with your roof at all — it's the fine print in your own policy. Some homeowners let their coverage lapse, some have a specific wind-and-hail deductible they didn't know about, and some have exclusions buried in the language they never read. If you don't meet the terms, the claim gets denied before the damage is ever discussed.
I get it — nobody sits down and reads their homeowner's policy for fun. But knowing what you're covered for, what your deductible actually is, and whether you've got Actual Cash Value or Replacement Cost coverage changes everything about how your claim plays out. The Texas Department of Insurance has solid free resources for understanding your rights and your policy terms.
- Confirm your policy is active and premiums are current
- Find your separate wind/hail deductible (it's often higher)
- Know if you have Replacement Cost or Actual Cash Value coverage
- Check for any exclusions specific to roof age or material
Pro Tip: Pull out your declarations page before you file. Knowing your deductible and coverage type up front keeps you from getting blindsided later.
5. Handling the Whole Fight Alone Without a Pro in Your Corner
The single biggest mistake I see is homeowners trying to go toe-to-toe with a professional adjuster all by themselves. No offense, but that adjuster does this every single day — they know the policy language, the loopholes, and exactly what to say to keep the payout low. You're at a disadvantage from the jump, and that's not your fault. It's just not a fair fight when it's one against a whole insurance company.
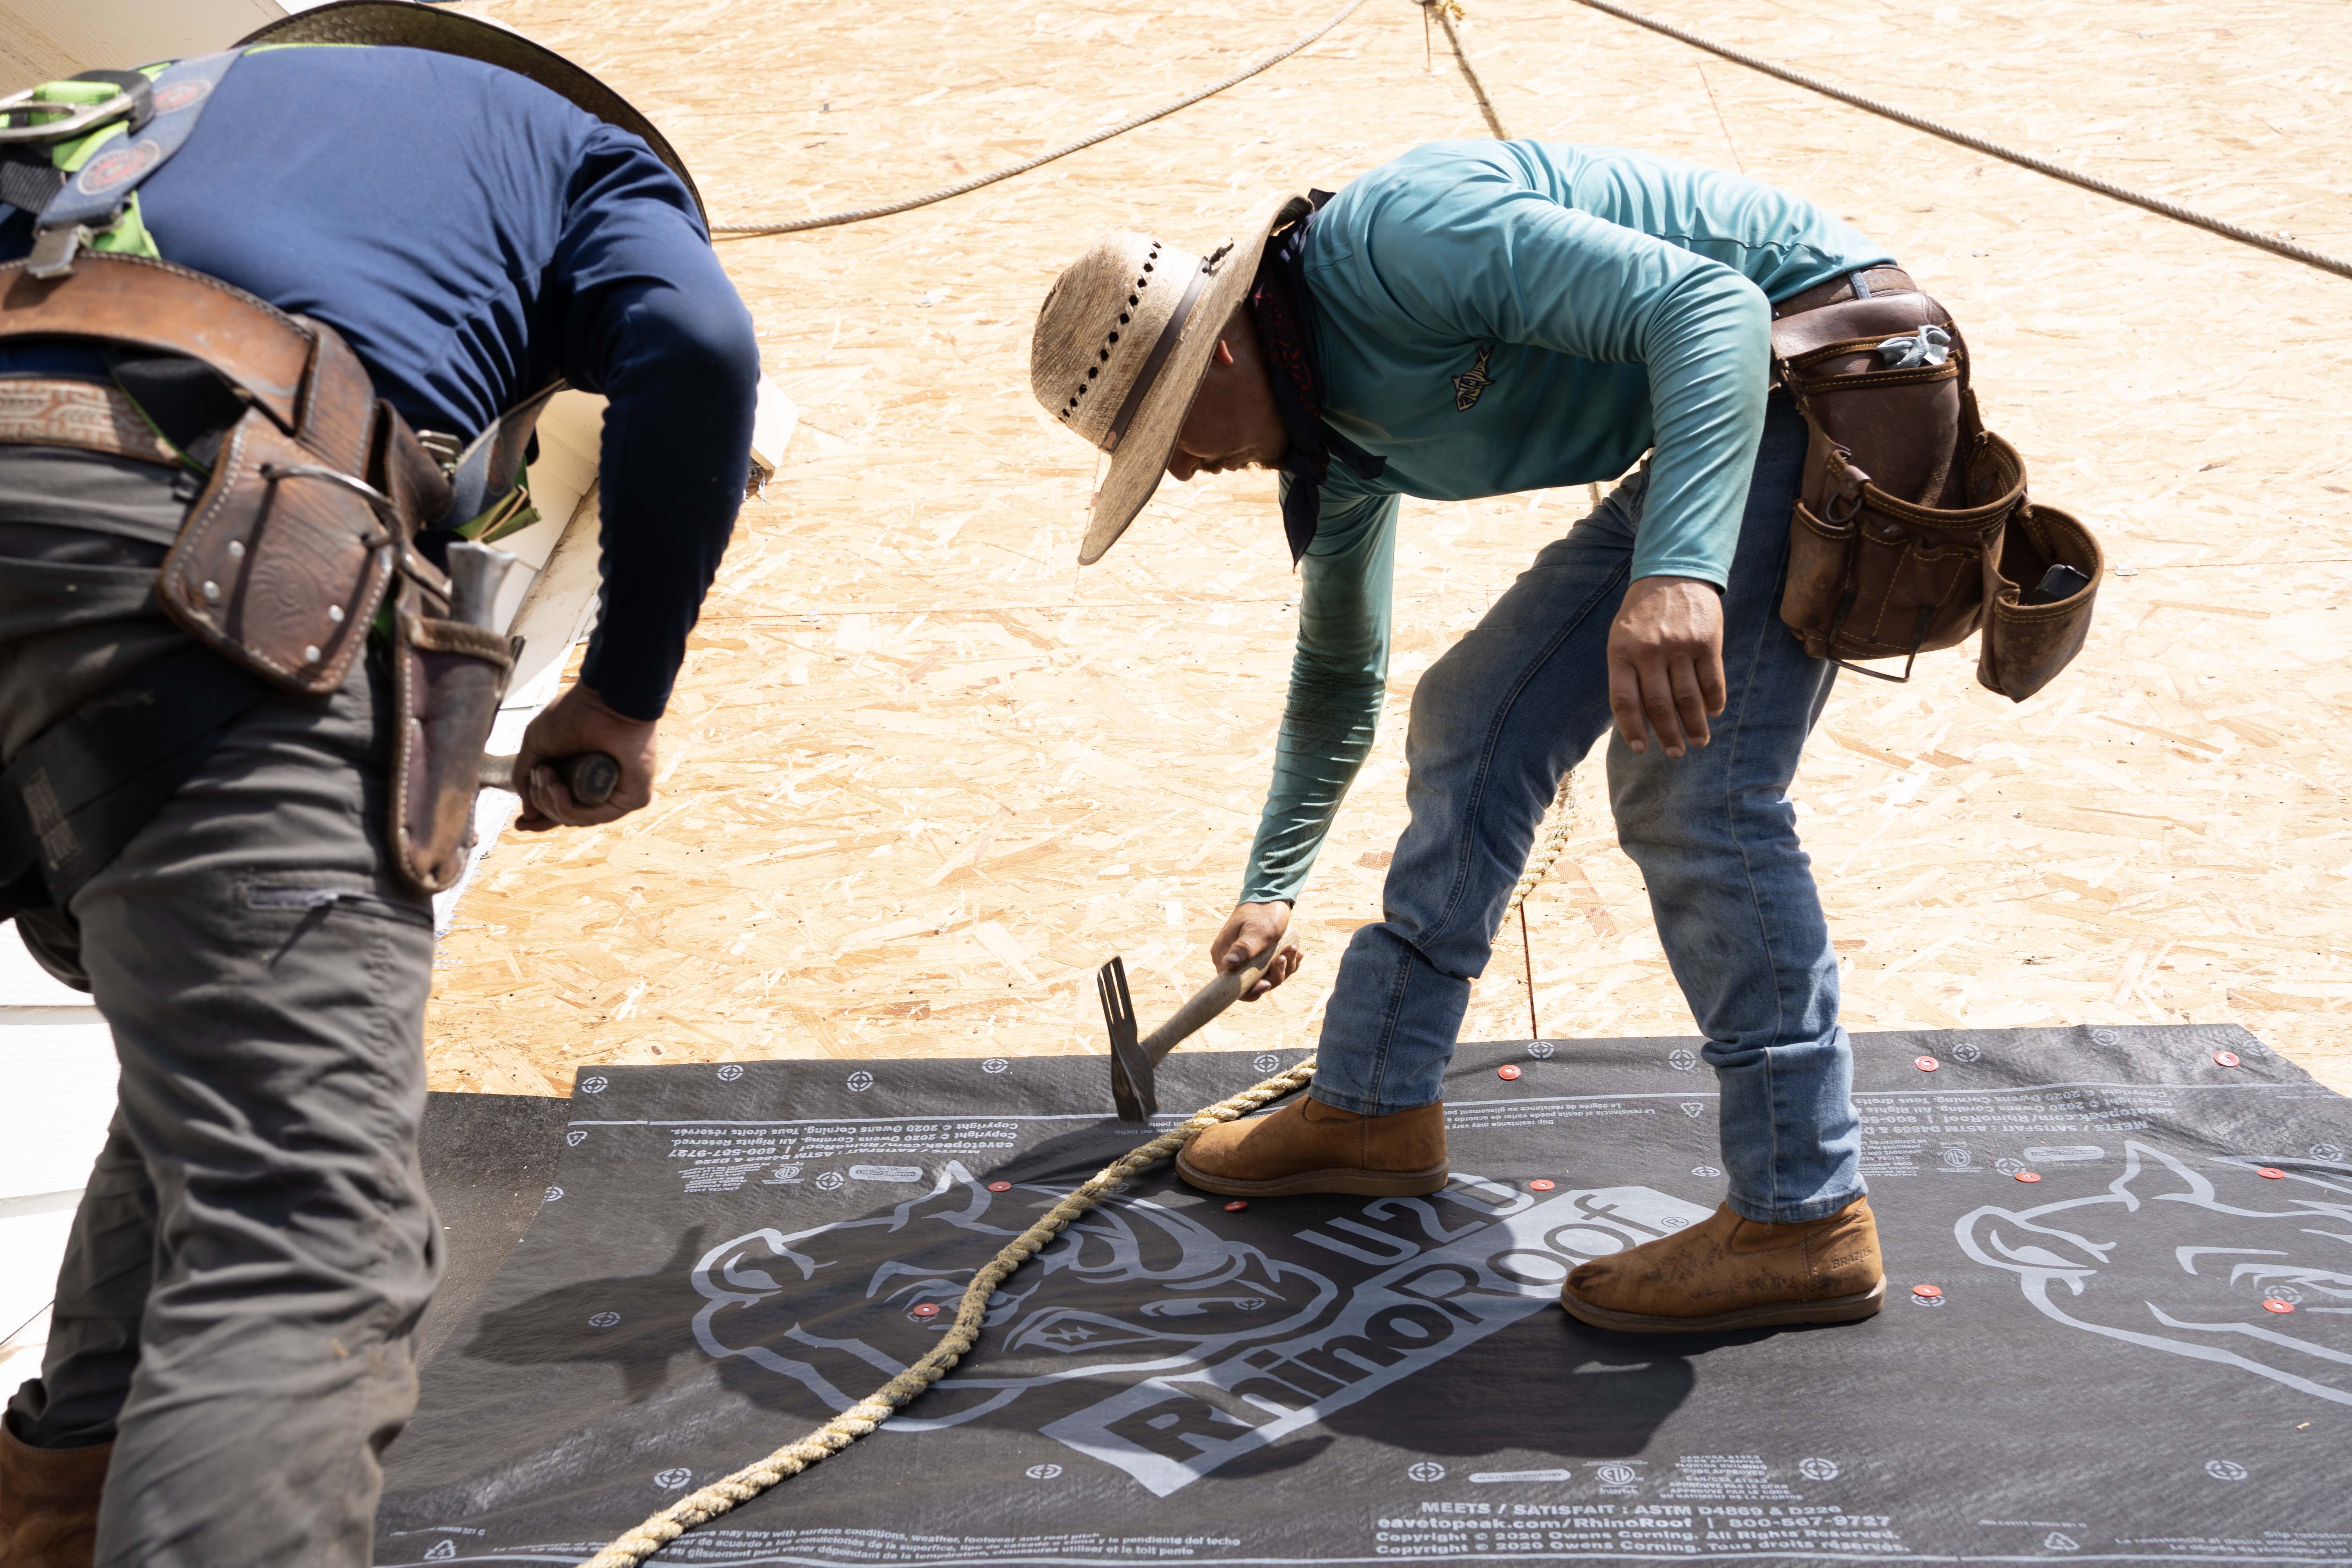
When we take on a claim, our whole approach is built around asking questions first to confirm there's a real problem we can solve — then we go to battle so you don't have to lift a finger. We meet the adjuster on your roof, we speak their language, and we make sure every bit of damage gets documented and accounted for.
- Adjusters negotiate for a living — you shouldn't have to
- A pro knows what evidence actually moves the needle
- Local, licensed contractors stick around to honor the warranty
- Out-of-town storm-chasers vanish and take your protection with them
Pro Tip: Never sign anything or accept a low estimate before getting a licensed local roofer to review it. That first offer is rarely the best one.
What I've learned about denied insurance claims after years in the field
I grew up poor in a little shack right here in Tyler, so I know exactly what it feels like to get taken advantage of by people who've got more power than you do. That's the whole reason I stand for honesty and integrity, period. When I see a homeowner get denied on a legitimate claim, it lights a fire in me — because I know most of those denials aren't about the roof, they're about nobody fighting for the person who owns it.
Texas doesn't even require a license to roof. A guy can slap a magnet on his truck and call himself a roofer, and there are a lot of fly-by-nights and slime balls out there taking people for a lot of money. We're the opposite of that. We're BBB A+ accredited, one of the only Owens Corning Platinum certified contractors in East Texas, and licensed by RCAT. When I give you my word, it's written in stone. You can read more about how we handle claims over at Advantage Roofing Company.
My framework is simple: give 110% of my attention to every single client so they don't have to lift a finger during the insurance process. That means I ask the questions first, confirm there's real damage I can solve, and then I go to battle with the adjuster on your behalf. We will never cut corners to save a dollar — because a bad install or a shorted claim leads to leaks, mold, and worse down the road.
What makes us different is that we're local and we stay local. We're not chasing storms across the country. When your roof needs us next year or five years from now, we'll still be right here in Tyler, Texas, ready to back up the work we did.
How Advantage Roofing Company helps overwhelmed homeowners win denied claims
If you got a denial letter, a lowball estimate, or you're just plain overwhelmed by the whole insurance mess, that's exactly the kind of situation we handle every day. We'll come out, get up on your roof, and give you an honest inspection with real documentation — the photos, the report, the storm-date evidence that adjusters actually respond to. Then we take that fight to your insurance company so you don't have to do it alone.
We specialize in new roofs and storm, hail, and wind damage restoration, including negotiating directly with insurance adjusters on your behalf. With over 400 Google reviews in the East Texas area and nearly 1,000 five-star reviews across Texas, we've earned a reputation for doing right by people — especially the ones who feel like the system is stacked against them.
Don't get taken by some out-of-town storm-chaser, and don't let a denial be the final word. Hit me up anytime — call or text (903) 939-3168 and I'll give you an honest opinion of exactly what I think. You can also learn more and reach out through advantageroofingcompany.com. We're right here at 16678 State Hwy. 155, Suite 300A, Tyler, Texas. Ain't nothing to it but to do it — let's go.
FAQ
What is the most common reason for roof insurance claims being denied?
The most common reason roof insurance claims are denied is a lack of proper documentation proving the damage was caused by a storm and not by age or wear-and-tear. At Advantage Roofing Company in Tyler, Texas, we solve this by fully documenting every bit of hail and wind damage with photos and a written report before the claim ever goes to the adjuster.
Can I appeal a denied roof insurance claim?
Yes, you can absolutely appeal a denied roof insurance claim, and many denials get overturned with the right documentation and a professional inspection. The key is proving the damage is storm-related with clear evidence — which is exactly the kind of fight Advantage Roofing Company takes on for East Texas homeowners.
How long do I have to file a roof damage claim in Texas?
Most Texas homeowner policies require you to file a roof damage claim within a specific window after the storm, so you should file as soon as possible rather than waiting. Filing too late is one of the most common denial reasons, which is why we recommend getting inspected right after any major storm in the Tyler area.
Why did the adjuster say my roof damage was wear-and-tear?
Adjusters often label storm damage as "wear-and-tear" because insurance policies don't cover normal aging, only sudden storm damage. A licensed roofer can document the specific signatures of hail and wind damage — round bruises, granule loss, and creased shingles — to prove it was the storm and not the calendar.
Should I hire a roofer to help with my insurance claim?
Yes, hiring a licensed local roofer to help with your insurance claim gives you someone who speaks the adjuster's language and fights for a fair payout on your behalf. Advantage Roofing Company in Tyler, Texas goes to battle with adjusters directly so homeowners don't have to lift a finger through the entire process.